India Solar Manufacturing: Growth, Scope & Government Subsidies
Share this article
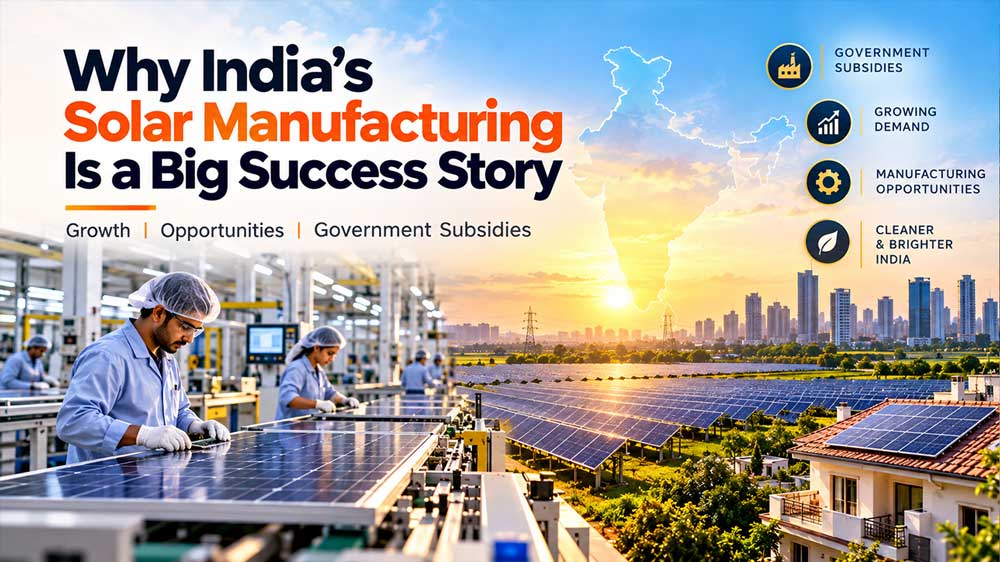
Why India’s Solar Manufacturing Is Becoming a Major Growth Story
India's solar industry has changed dramatically over the past decade. What was once heavily dependent on imported solar equipment is developing into a large domestic manufacturing ecosystem, supported by government policy, rising electricity demand and the country's expanding renewable-energy capacity.
The scale of the change is significant. Solar PV module manufacturing capacity listed under India's Approved List of Models and Manufacturers (ALMM) reached 100 GW in August 2025, compared with about 2.3 GW in 2014. Solar cell manufacturing capacity also reached about 25 GW by March 2025, up from less than 1.2 GW in 2014.
But the more important question is what comes next.
Can India turn this manufacturing expansion into a globally competitive solar industry—and what opportunities does the growing domestic market create for businesses and investors?
Why Solar Manufacturing Is Growing in India
Several factors are working together.
1. India's Solar Demand Is Expanding
India's installed solar capacity reached 168.04 GW by August 31, 2026, including 123.99 GW of ground-mounted solar, 32.59 GW of grid-connected rooftop solar, 4.83 GW of solar capacity within hybrid projects and 6.63 GW of off-grid solar.
The government has also set a broader target of 500 GW of non-fossil electricity capacity by 2030. By July 31, 2026, India had already crossed 300 GW of non-fossil capacity, including 164.59 GW of solar.
That creates a large long-term domestic market for:
Solar modules
Solar cells
Inverters
Mounting structures
Batteries and storage
Solar EPC services
Rooftop systems
Operation and maintenance
Solar financing
Monitoring software
Demand is therefore not limited to large solar parks.
2. Government Policy Has Changed the Manufacturing Economics
India's manufacturing push has been supported by a combination of financial incentives and market-access policies.
One of the most important initiatives is the Production Linked Incentive (PLI) Scheme for High Efficiency Solar PV Modules.
The scheme has a total outlay of ₹24,000 crore and provides production-linked incentives to selected manufacturers for five years after commissioning, based on the manufacture and sale of qualifying high-efficiency solar PV modules.
The PLI programme has been divided into two major tranches:
Tranche I: ₹4,500 crore
Tranche II: ₹19,500 crore
MNRE says Tranche I selected manufacturers for 8,737 MW of fully integrated capacity, while Tranche II selected 11 bidders for approximately 39,600 MW of fully or partially integrated manufacturing capacity.
The objective goes beyond increasing module assembly.
The policy is designed to encourage technology, integration, local sourcing and greater manufacturing capability across the value chain.
3. ALMM Has Created a Domestic Manufacturing Market
The Approved List of Models and Manufacturers (ALMM) is another important policy mechanism.
Under the current framework, solar PV modules used in government projects, government-assisted projects, government schemes and programmes, as well as specified open-access and net-metering projects, must meet the applicable ALMM requirements. MNRE has also established an ALMM framework for solar PV cells.
This creates a significant market-access advantage for eligible domestic manufacturers.
The policy has also been extended deeper into the supply chain. From June 1, 2026, applicable projects commissioned after that date are subject to ALMM List-II requirements for solar cells, subject to specified provisions and case-by-case relief for certain existing projects.
The underlying strategy is clear:
Build domestic capacity → create demand for compliant products → encourage investment → develop a local supply chain.
4. India Is Moving From Modules Toward an Integrated Supply Chain
There is an important weakness in India's solar manufacturing story, however.
Module manufacturing has expanded much faster than upstream manufacturing.
The NITI Aayog analysis notes that India remains dependent on imports for important upstream materials such as polysilicon and wafers, even though module and cell capacity has grown rapidly.
The solar manufacturing chain broadly consists of:
Polysilicon → Ingot → Wafer → Cell → Module → Solar Project
India has made considerable progress in the final stages, but deeper integration is still developing.
That creates another opportunity.
Companies capable of moving into wafers, ingots, advanced cells, manufacturing equipment and other upstream components could potentially address one of the industry's biggest remaining gaps.
The Scope of Solar Panels in India
The domestic opportunity is much larger than utility-scale solar farms.
Rooftop Solar
Residential rooftop solar is becoming an increasingly important market.
Under PM Surya Ghar: Muft Bijli Yojana, the Union government is targeting rooftop solar for one crore households. The programme has a total outlay of ₹75,021 crore.
As of July 22, 2026, the government reported approximately 39.72 lakh rooftop solar systems installed, covering about 48.03 lakh households.
This creates opportunities for:
Solar installers
EPC companies
Local dealers
Module manufacturers
Inverter suppliers
Battery-storage providers
Solar financing companies
Maintenance providers
For small and medium businesses, rooftop solar can therefore be a more accessible entry point than building a large utility-scale project.
Solar for Agriculture
Agriculture represents another major opportunity.
Under PM-KUSUM, the government has supported decentralized solar plants and solarisation of agricultural pumps.
The scheme includes:
Component A — decentralized renewable-energy plants
Component B — standalone solar agricultural pumps
Component C — solarisation of grid-connected agricultural pumps and feeders
The national portal reported that, as of August 31, 2026, more than 11.80 lakh standalone solar pumps had been installed under Component B, while more than 16.28 lakh pumps had been solarised under the feeder-level Component C programme.
For rural India, solar is therefore not simply an electricity-generation technology. It can also become part of irrigation, agricultural infrastructure and rural energy economics.
Solar for Commercial and Industrial Businesses
Commercial and industrial consumers represent another large market.
Factories, warehouses, shopping centres, hotels, hospitals and offices can use rooftop or open-access solar to reduce exposure to conventional electricity costs.
This creates opportunities beyond panel manufacturing.
The broader ecosystem includes:
Solar EPC + financing + installation + energy management + storage + maintenance
That means the solar opportunity can extend to companies that never manufacture a single solar panel.
What Subsidies Are Available From the Indian Government?
The biggest mistake is to assume that every solar installation receives the same subsidy.
Subsidies depend on the type of project, consumer category, scheme and state.
PM Surya Ghar — Residential Rooftop Solar
For eligible residential rooftop systems, the current central financial assistance structure provides:
System SizeCentral Subsidy1 kW₹30,0002 kW₹60,0003 kW₹78,000Above 3 kWMaximum ₹78,000
The central assistance is structured at ₹30,000/kW for the first 2 kW and ₹18,000/kW for the additional capacity up to 3 kW. The central subsidy is capped at 3 kW.
The government also reported in July 2026 that eligible households could access collateral-free loans at a concessional rate of repo rate plus 50 basis points, which was 5.75% at the time of that announcement.
What About State Government Subsidies?
This is where the picture becomes more complicated.
States can provide additional incentives, capital subsidies, financing support, land-related benefits, net-metering arrangements or other renewable-energy incentives.
But there is no single nationwide "state subsidy" amount.
Delhi
Delhi is a useful example of an additional state-level incentive.
The Delhi Solar Portal currently lists a state capital subsidy for residential consumers of up to ₹26,000 per kW, subject to its stated conditions and an overall maximum of ₹78,000. It also lists a separate subsidy framework for Group Housing Societies and RWAs, including ₹11,000/kWp for qualifying common-area systems, subject to the scheme's conditions.
This is in addition to the applicable central PM Surya Ghar assistance, meaning an eligible Delhi household may have access to both central and state support.
Maharashtra
Maharashtra has taken a broader policy approach to renewable energy.
The Maharashtra Renewable Energy Policy 2020 includes targets for solar generation and rooftop solar. MEDA reported 3,203.61 MW of rooftop solar commissioned in Maharashtra by March 31, 2025, alongside 5,421.196 MW of solar power projects overall.
Maharashtra's solar-agriculture-pump framework has also involved both central and state financial support. MEDA documentation describes a structure involving central assistance, state government support and a beneficiary contribution, with the exact arrangement depending on the programme and beneficiary category.
Karnataka
Karnataka's DISCOM processes are integrated with the national rooftop-solar framework.
For example, HESCOM's PM Surya Ghar information lists the central assistance of ₹30,000/kW for the first 2 kW and ₹18,000/kW for the additional capacity up to 3 kW, reaching the ₹78,000 maximum.
The state/DISCOM process also includes application, feasibility approval, PPA and empanelled-vendor requirements.
Gujarat
Gujarat has developed renewable-energy infrastructure and a single-window process through GUVNL's Akshay Urja Setu, covering processes involving GEDA, GETCO, DISCOMs and other approvals for renewable-energy projects.
The important point is that state support is not always simply a cash subsidy. It can also come through project approvals, grid connectivity, renewable-energy policies, land frameworks, tenders and administrative support.
A Business Opportunity Beyond Solar Panels
One of the most important points for entrepreneurs is that the solar boom does not mean only "open a solar panel factory."
There are opportunities across the value chain.
Manufacturing
Solar cells
Solar modules
Inverters
Mounting structures
Cables
Junction boxes
Solar glass
Batteries
Manufacturing equipment
Installation
Rooftop EPC
Industrial solar
Commercial solar
Agricultural solar
Solar pumps
Rural solar systems
Services
Operations and maintenance
Remote monitoring
Cleaning
Performance management
Solar financing
Insurance
Energy audits
Engineering and consulting
Technology
Solar monitoring software
AI-based predictive maintenance
Energy-management systems
Smart inverters
Battery-management systems
Digital project management
The strongest business opportunities may eventually sit between these categories rather than inside only one.
Why India's Solar Manufacturing Story Is Important
India's solar manufacturing expansion has happened because policy and market demand have reinforced each other.
The government has created incentives through PLI, market-access requirements through ALMM and demand-side programmes such as PM Surya Ghar and PM-KUSUM.
At the same time, India's electricity demand and renewable-energy targets are creating a large underlying market.
The results are visible in the numbers: ALMM-listed module manufacturing capacity reached 100 GW in 2025, while cumulative solar installations reached 168.04 GW by August 2026.
But the unspoken part of the story is equally important.
100 GW of module capacity does not mean India has become completely self-sufficient in solar manufacturing.
Upstream dependence on imported wafers and polysilicon remains a structural challenge. NITI Aayog has highlighted this gap, along with the need for deeper integration and greater competitiveness.
That means the next chapter may not be about simply producing more panels.
It may be about producing better cells, wafers, equipment and components at globally competitive costs.
What Is the Future Scope of Solar in India?
The opportunity could expand across five major areas:
1. Residential rooftop solar
Millions of households remain potential customers.
2. Industrial and commercial solar
Businesses are likely to remain important customers for distributed and open-access renewable energy.
3. Utility-scale solar
Large solar parks will continue to drive significant capacity additions.
4. Agriculture
Solar pumps and feeder solarisation can create a major rural market.
5. Solar plus storage
As renewable penetration increases, batteries and other storage technologies become increasingly important for managing intermittency and electricity demand.
This suggests that the future solar industry will be much larger than the traditional panel → installation → electricity model.
It is increasingly becoming an ecosystem involving manufacturing, finance, software, storage, grid infrastructure and energy services.
The Bigger Business Opportunity
India's solar industry has reached a point where the opportunity is shifting.
The first phase was largely about building solar capacity.
The next phase is increasingly about building the supply chain around that capacity.
For entrepreneurs, manufacturers and investors, that distinction matters.
The biggest opportunities may emerge in areas where India still depends heavily on imports or where the rapid growth of solar creates new operational problems.
That includes advanced solar cells, wafers, inverters, energy storage, recycling, manufacturing equipment, rooftop financing, digital monitoring and maintenance.
India has already demonstrated that it can rapidly expand solar manufacturing capacity.
The next test is whether that capacity can become cost-competitive, technologically advanced and deeply integrated across the entire solar value chain.
Tags